 ultimate-guide
Navigating Insurance Claims Without Stress
Table of Contents
- What Happens Immediately After an Accident
- Understanding Your Insurance Policy Coverage
- Insurance Claim Documentation Checklist
- How Long Does an Insurance Claim Take
- What Not to Say to Insurance Adjusters
- Benefits of Independent Accident Support
- Managing Stress and Recovery During Your Claim
- Conclusion
- Frequently Asked Questions
Last Updated: September 4, 2026
What Happens Immediately After an Accident
The moments right after a collision are chaotic, and navigating insurance claims without stress starts with knowing exactly what to do first. Your priority is safety, then information, then communication. The actions you take in the first 30 minutes can shape the entire claims process, so having a clear mental script matters more than you might think.
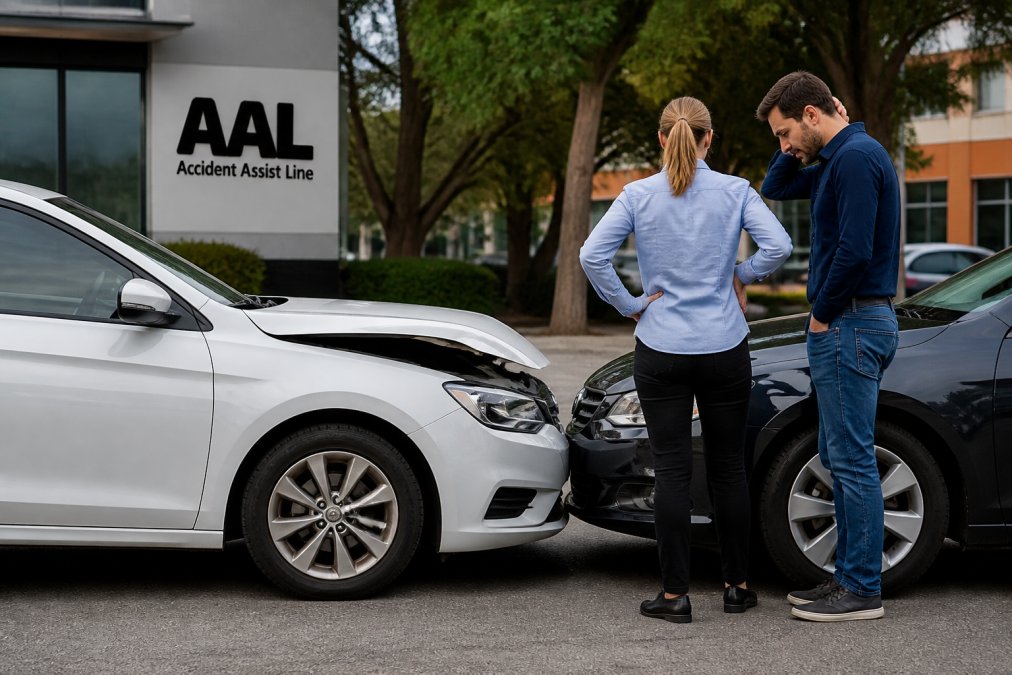
At Accident Assist Line, the immediate sequence is simple: move to a safe location if possible, turn on hazard lights, check everyone for injuries, and call emergency services if needed. Do not leave the scene, and do not move your vehicle until authorities advise it is safe.
Once you are safe, exchange details with the other driver. This includes names, contact numbers, registration numbers, and insurance policy information. Take photos of the damage to both vehicles and the surrounding scene. This evidence is the foundation of your insurance claim documentation checklist, and it will protect you later if the other party disputes what happened.
Understanding Your Insurance Policy Coverage
Most drivers do not understand their insurance policy until they need to claim, and that is exactly the wrong time to learn. Your policy documents outline your coverage limits, your excess, and the situations where you are protected. Before you even need to claim, you should know whether you hold comprehensive, third-party property, or third-party fire and theft cover.
The fine print matters more than the front page. Check whether your policy includes a hire car benefit, whether your repairer is chosen by you or the insurer, and whether there are time limits for lodging a claim. Many policies require you to notify the insurer within a specific period, and missing that window can complicate your claim.
A common mistake is assuming your insurer handles everything automatically. In practice, you remain the policyholder and the claimant, which means you carry the responsibility for providing evidence and responding to requests. This is why many drivers choose independent accident support, since it shifts the administrative burden while you focus on recovery.
Insurance Claim Documentation Checklist
Your insurance claim documentation checklist is the single most useful tool for navigating insurance claims without pressure. Insurance is a paperwork-heavy process, and missing documents cause most delays. Gather everything systematically, and the process becomes far more manageable.
Start with your incident report, whether that is a police report number or your own written account of what happened. Add your photos of vehicle damage, the other driver's details, and any witness contact information. Then include your insurance policy number and the other party's policy details if you have them.
- Photos of damage to all vehicles involved
- Written account of the incident timeline
- Contact details for witnesses
- Police report reference number if applicable
- Insurance policy numbers for all parties
- Medical reports if anyone was injured
- Any correspondence with the insurer or other party
Organising these documents digitally helps. Store photos and scans in a dedicated folder on your phone, and keep a communication log of every call and email with your insurer. This record-keeping is not just useful, it is your protection if a dispute arises about what was said or promised.
How Long Does an Insurance Claim Take
A straightforward claim with clear fault and complete documentation can be settled within a few weeks, while complex claims involving injuries or disputed liability can stretch for months. The timeline depends mostly on how quickly you provide evidence and how responsive the other party's insurer is.
The standard progression moves through lodgement, assessment, repair or payout, and finalisation. Your insurer must assess the claim once you submit your proof of loss, but they can only work with the information you provide. Delays usually come from incomplete documentation, unreachable witnesses, or disagreements about who was at fault.
What most guides miss is the dispute resolution pathway. If your claim is denied or the settlement offer falls short of your expectations, you have clear recourse. First, request a detailed written explanation of the decision from your insurer, this is your right under the Insurance Contracts Act 1984 (Cth). Review the explanation against your policy wording and the evidence you submitted. If you believe the decision is wrong, lodge a formal dispute with your insurer's internal dispute resolution (IDR) team within the timeframe specified in their response (typically 30 days).
If the IDR process does not resolve the matter to your satisfaction, you can escalate to the Australian Financial Complaints Authority (AFCA), an independent external dispute resolution scheme (afca.org.au). AFCA can investigate your complaint at no cost to you and has the power to order your insurer to pay compensation up to $1 million for most claims (afca.org.au). The AFCA process typically takes 6-12 weeks, depending on complexity (afca.org.au).
For claims involving significant amounts or complex liability questions, seeking advice from an insurance lawyer or claims advocate before escalating can strengthen your position. They can review whether your insurer has correctly interpreted your policy, whether the assessment was thorough, and whether your evidence supports a higher settlement. This professional input often resolves disputes without needing to proceed to AFCA.
The emotional timeline differs from the administrative one. The claim may resolve quickly, but the stress of driving again or dealing with ongoing recovery can persist. That is why proactive communication matters. Regular follow-ups with your insurer, and keeping your own records of those conversations, keeps the process moving and gives you a sense of control. Knowing you have a clear escalation path if needed also reduces the anxiety of feeling trapped in an unfair outcome.
What Not to Say to Insurance Adjusters
Insurance adjusters are professionals doing a job, but they are also trained to identify statements that could reduce the insurer's liability. Knowing what not to say is as important as knowing what to say. The golden rule is to stick to the facts and avoid admitting fault, even if you think you caused the accident.
Never say "I'm sorry" at the scene in a way that implies fault, and never speculate about what happened if you are unsure. Phrases like "I didn't see them" or "I was distracted" can be interpreted as admissions. You should also avoid giving a recorded statement until you have reviewed your policy and understood your obligations.
- Avoid admitting fault, even politely
- Do not guess about speed, distances, or timing
- Decline to provide a recorded statement immediately
- Do not sign anything without reading it fully
- Keep answers brief and factual
- Redirect questions about injuries to medical professionals
A significant benefit of independent accident support is having an advocate who understands these conversations. Rather than navigating insurance claims alone and risking a misstatement, you can have a service coordinate the details while you focus on what matters. This is not about hiding anything, it is about ensuring your rights as a policyholder are protected.
Benefits of Independent Accident Support
The benefits of independent accident support become obvious when you compare the experience to managing everything yourself. An independent service operates separately from insurance companies, which means their guidance is aligned with your interests, not the insurer's bottom line. They organise towing, arrange repairs, and can provide a hire car while yours is off the road.
This independence matters because it gives you options. Your insurer may direct you to their preferred repairer, but an independent service can connect you with quality repair shops and coordinate the logistics without the insurer's constraints. This can include arranging a hire car immediately, rather than waiting for approval.
For drivers navigating insurance claims without stress, the practical difference is time and effort. Instead of chasing phone calls and completing forms during business hours, you can access round-the-clock support with a callback in under 30 seconds. That immediacy, combined with no forms and no wait times, transforms a stressful administrative burden into a managed process.
Managing Stress and Recovery During Your Claim
The psychological impact of an accident often outlasts the physical repairs. Managing stress and recovery during your claim is a legitimate part of the process, and acknowledging it is the first step. Anxiety about costs, transport, and future driving can build up, particularly while the claim is unresolved. Unlike the administrative steps of filing a claim, the emotional toll is rarely addressed in insurance guides, yet it is often the hardest part.
Grounding Techniques for Claims-Related Anxiety
When you are waiting for assessor updates, dealing with phone calls, or reviewing correspondence, anxiety can spike. Three evidence-based grounding techniques can help you stay present and reduce overwhelm:
The 5-4-3-2-1 Sensory Technique. When you feel anxiety rising, pause and identify five things you can see, four you can touch, three you can hear, two you can smell, and one you can taste. This redirects your nervous system from the "what if" of the claim to the present moment. Use this before making calls to your insurer or reviewing claim documents.
Box Breathing. Breathe in for a count of four, hold for four, exhale for four, hold for four. Repeat five times. This activates your parasympathetic nervous system and reduces the physical symptoms of stress, racing heart, shallow breathing, that often accompany claim-related conversations.
Cognitive Reframing. When you catch yourself thinking "This will never be resolved" or "The insurer is deliberately stalling," pause and ask: What is the evidence for this thought? What would I tell a friend in this situation? Often, the claim is progressing normally, but anxiety disrupts your perception of the timeline.
Structuring Your Claim Work
Administrative overwhelm amplifies stress. Set specific "claim time" blocks, perhaps Tuesday and Thursday mornings, rather than letting claim tasks interrupt your entire week. Outside those blocks, do not check emails or take calls about the claim. This boundary reduces the mental load and prevents the claim from colonising your thoughts.
Keep a simple log of your emotional state alongside your claim progress. Note when you felt most anxious and what triggered it. Often, you will find that anxiety peaks around specific milestones (waiting for the assessment, receiving the offer) rather than being constant. Recognising the pattern helps you prepare coping strategies in advance.
When to Seek Professional Support
If you were injured in the accident, your insurer may cover psychology or counselling as part of your claim. Ask your insurer explicitly whether trauma counselling is covered under your policy or whether they will fund sessions with a psychologist. Many policies do cover this, but you have to ask.
If you are experiencing persistent anxiety, sleep disruption, or avoidance of driving weeks after the incident, contact your GP. Post-accident anxiety is common and treatable. Your doctor can refer you to a psychologist under the Medicare Better Access scheme, which provides subsidised sessions.
Vulnerable customers, older drivers, those with pre-existing anxiety or depression, or those injured in the incident, may need extra patience and assistance. Insurance is a compliance-heavy industry with its own timelines and jargon, and that complexity can feel overwhelming when you are already stressed. Using a dedicated service that handles the coordination lets you step back from the fine print and focus on your wellbeing.
Conclusion
Navigating insurance claims without stress is not about avoiding the process, it is about approaching it with the right tools and support. You need clear documentation, honest communication, and an understanding of your policy, but you do not need to carry the entire burden yourself. The emotional load of an accident is real, and reducing the administrative weight is part of your recovery.
Accident Assist Line provides immediate, independent support across Victoria, New South Wales, Queensland, and the ACT. With 24/7 availability, no forms, and a callback in under 30 seconds, we organise towing, repairs, and hire cars so you can get back on the road quickly. Get started with Accident Assist Line and let us handle the process while you focus on moving forward.
Frequently Asked Questions
What's the biggest mistake people make when lodging an insurance claim?
Failing to document the incident thoroughly from the start. Many claimants don't gather photos, witness details, or medical reports immediately after an accident, making it harder to prove their case later. The first 24 hours are critical. Take photos of all vehicle damage, road conditions, and any injuries. Get contact details from witnesses and the other driver. Report the incident to your insurer promptly, delays can affect your claim's validity. Keep a detailed record of everything that happens next, including dates, times, and names of people you speak with.
What should you avoid saying to an insurance claims adjuster?
Never admit fault, apologise for the incident, or speculate about what happened. Avoid saying things like 'I wasn't paying attention' or 'I probably could have stopped sooner.' Don't minimise your injuries by saying 'I'm fine' if you're actually in pain, injuries can develop over days or weeks. Don't accept a settlement offer on the spot without reviewing it carefully. Stick to facts: what you saw, heard, and experienced. Let your documentation and the adjuster's investigation determine liability, not your words.
How can independent accident support reduce stress during the claims process?
An independent accident support service handles the coordination between you, your insurer, repair shops, and hire car providers. Instead of juggling multiple phone calls and paperwork, you have one point of contact managing everything. They provide unbiased guidance, they don't work for your insurer, so they advocate for your interests. Many services offer 24/7 availability, meaning you get help immediately after an accident, not during business hours. This reduces decision fatigue, speeds up recovery, and removes the anxiety of navigating complex insurance terminology and processes alone.
What documentation is essential for a successful insurance claim?
You'll need the incident report (police report if applicable), photos of vehicle damage and the accident scene, the other driver's details and insurance information, witness contact information, medical reports if injured, repair quotes, receipts for expenses incurred, and your policy documents. Keep a communication log with dates and times of all conversations with your insurer, adjuster, and repair shop. Organise these digitally or in a folder, don't rely on memory. The more complete your documentation, the faster your claim progresses and the less likely disputes will arise.
How long does an insurance claim typically take after a vehicle accident?
Simple claims with clear liability can be resolved in 2-4 weeks. More complex claims involving multiple vehicles, injuries, or disputed liability may take 6-12 weeks or longer. The timeline depends on how quickly you provide documentation, how fast the adjuster investigates, and whether repair work is straightforward. Prompt notification to your insurer, complete documentation, and proactive communication can significantly speed up the process. Independent support services can help coordinate faster resolution by ensuring all parties have what they need without delays.
What are your rights when dealing with an insurance provider?
You have the right to clear information about your policy coverage and claim status. Your insurer must handle your claim fairly and promptly, and they cannot unreasonably deny a valid claim. You can request a detailed explanation if your claim is denied. If you disagree with a decision, you can lodge a complaint with the insurer's internal disputes team, and if unresolved, escalate to the Australian Financial Complaints Authority (AFCA). You also have the right to seek independent legal or professional advice, and to have a representative (like an accident support service) advocate on your behalf.
What should I do immediately after a vehicle accident to protect my claim?
First, check for injuries and call emergency services if needed. Move to a safe location if possible. Call the police if there's significant damage or injury. Exchange details with the other driver (name, phone, address, licence plate, insurance details). Take photos of all vehicle damage, the accident scene, road conditions, and any visible injuries. Don't admit fault or sign anything except police documents. Call your insurer as soon as possible, most policies require notification within a set timeframe. Keep all receipts and documents related to the incident.
This article was written using GrandRanker
Frequently Asked Questions
Q: What's the biggest mistake people make when lodging an insurance claim?
A: Failing to document the incident thoroughly from the start. Many claimants don't gather photos, witness details, or medical reports immediately after an accident, making it harder to prove their case later. The first 24 hours are critical. Take photos of all vehicle damage, road conditions, and any injuries. Get contact details from witnesses and the other driver. Report the incident to your insurer promptly—delays can affect your claim's validity. Keep a detailed record of everything that happens next, including dates, times, and names of people you speak with.
Q: What should you avoid saying to an insurance claims adjuster?
A: Never admit fault, apologise for the incident, or speculate about what happened. Avoid saying things like 'I wasn't paying attention' or 'I probably could have stopped sooner.' Don't minimise your injuries by saying 'I'm fine' if you're actually in pain—injuries can develop over days or weeks. Don't accept a settlement offer on the spot without reviewing it carefully. Stick to facts: what you saw, heard, and experienced. Let your documentation and the adjuster's investigation determine liability, not your words.
Q: How can independent accident support reduce stress during the claims process?
A: An independent accident support service handles the coordination between you, your insurer, repair shops, and hire car providers. Instead of juggling multiple phone calls and paperwork, you have one point of contact managing everything. They provide unbiased guidance—they don't work for your insurer, so they advocate for your interests. Many services offer 24/7 availability, meaning you get help immediately after an accident, not during business hours. This reduces decision fatigue, speeds up recovery, and removes the anxiety of navigating complex insurance terminology and processes alone.
Q: What documentation is essential for a successful insurance claim?
A: You'll need the incident report (police report if applicable), photos of vehicle damage and the accident scene, the other driver's details and insurance information, witness contact information, medical reports if injured, repair quotes, receipts for expenses incurred, and your policy documents. Keep a communication log with dates and times of all conversations with your insurer, adjuster, and repair shop. Organise these digitally or in a folder—don't rely on memory. The more complete your documentation, the faster your claim progresses and the less likely disputes will arise.
Q: How long does an insurance claim typically take after a vehicle accident?
A: Simple claims with clear liability can be resolved in 2–4 weeks. More complex claims involving multiple vehicles, injuries, or disputed liability may take 6–12 weeks or longer. The timeline depends on how quickly you provide documentation, how fast the adjuster investigates, and whether repair work is straightforward. Prompt notification to your insurer, complete documentation, and proactive communication can significantly speed up the process. Independent support services can help coordinate faster resolution by ensuring all parties have what they need without delays.
Q: What are your rights when dealing with an insurance provider?
A: You have the right to clear information about your policy coverage and claim status. Your insurer must handle your claim fairly and promptly, and they cannot unreasonably deny a valid claim. You can request a detailed explanation if your claim is denied. If you disagree with a decision, you can lodge a complaint with the insurer's internal disputes team, and if unresolved, escalate to the Australian Financial Complaints Authority (AFCA). You also have the right to seek independent legal or professional advice, and to have a representative (like an accident support service) advocate on your behalf.
Q: What should I do immediately after a vehicle accident to protect my claim?
A: First, check for injuries and call emergency services if needed. Move to a safe location if possible. Call the police if there's significant damage or injury. Exchange details with the other driver (name, phone, address, licence plate, insurance details). Take photos of all vehicle damage, the accident scene, road conditions, and any visible injuries. Don't admit fault or sign anything except police documents. Call your insurer as soon as possible—most policies require notification within a set timeframe. Keep all receipts and documents related to the incident.